
The prospectus OPay filed with the Securities and Exchange Commission contains a figure that would be unremarkable in Silicon Valley and startling in Lagos: 339.1 billion dollars of gross transaction value in the first six months of the year, more than double the 139.3 billion dollars recorded in the same period of 2025.
The company, which began as a mobile payments app for Nigerian consumers, applied on October 9 to list American depositary shares on the New York Stock Exchange, targeting a valuation of about 4 billion dollars. It reported revenue of 467.1 million dollars for the six months to June 30, up from 197.5 million dollars a year earlier, and net income of more than 90 million dollars.
The number that explains those results is not the transaction volume. It is the loan book. OPay’s filing attributes much of its revenue growth to loan financing, which has become its largest single source of income, ahead of the payment fees that built the business. A payments app that processed other people’s money has become a lender in its own right, and it is asking American public-market investors to underwrite the credit risk that comes with that shift.
That framing is doing work in the deal as much as in the accounts. Standard Bank Group, Africa’s largest lender by assets, disclosed a subscription agreement through its subsidiary Stanbic Africa Holdings to take up to a 4.99% stake in OPay for as much as 200 million dollars. The investment is expected to close alongside or shortly after the listing, subject to the offering being completed and approvals being obtained, the bank said in a statement. Bloomberg reported that OPay intends to raise about 500 million dollars in total, including the private placement.
The partnership the two sides described extends beyond capital. Standard Bank said they intend to explore digital banking, merchant services and the distribution of selected bank products through OPay’s platform in African markets, which are prospective areas of cooperation rather than services already running. For the bank, the appeal is a consumer and merchant network it did not have to build. For OPay, the appeal is an institutional partner whose presence in a prospectus is easier for a New York investor to price than a growth rate in naira.
The shareholder register reads as a tour of two capital markets. Zhou Yahui, the Chinese billionaire who founded the Opera browser, is the controlling figure behind the company; Opera spun the business out and holds a stake that it has marked in its own filings. SoftBank’s Vision Fund 2 led a 400 million dollar round in 2021 that valued OPay at 2 billion dollars, according to press reports at the time, and IDG Capital and a Meituan-linked entity are also on the register. A listing at 4 billion dollars would double the mark of five years ago without the intervening enthusiasm that lifted other fintech valuations.
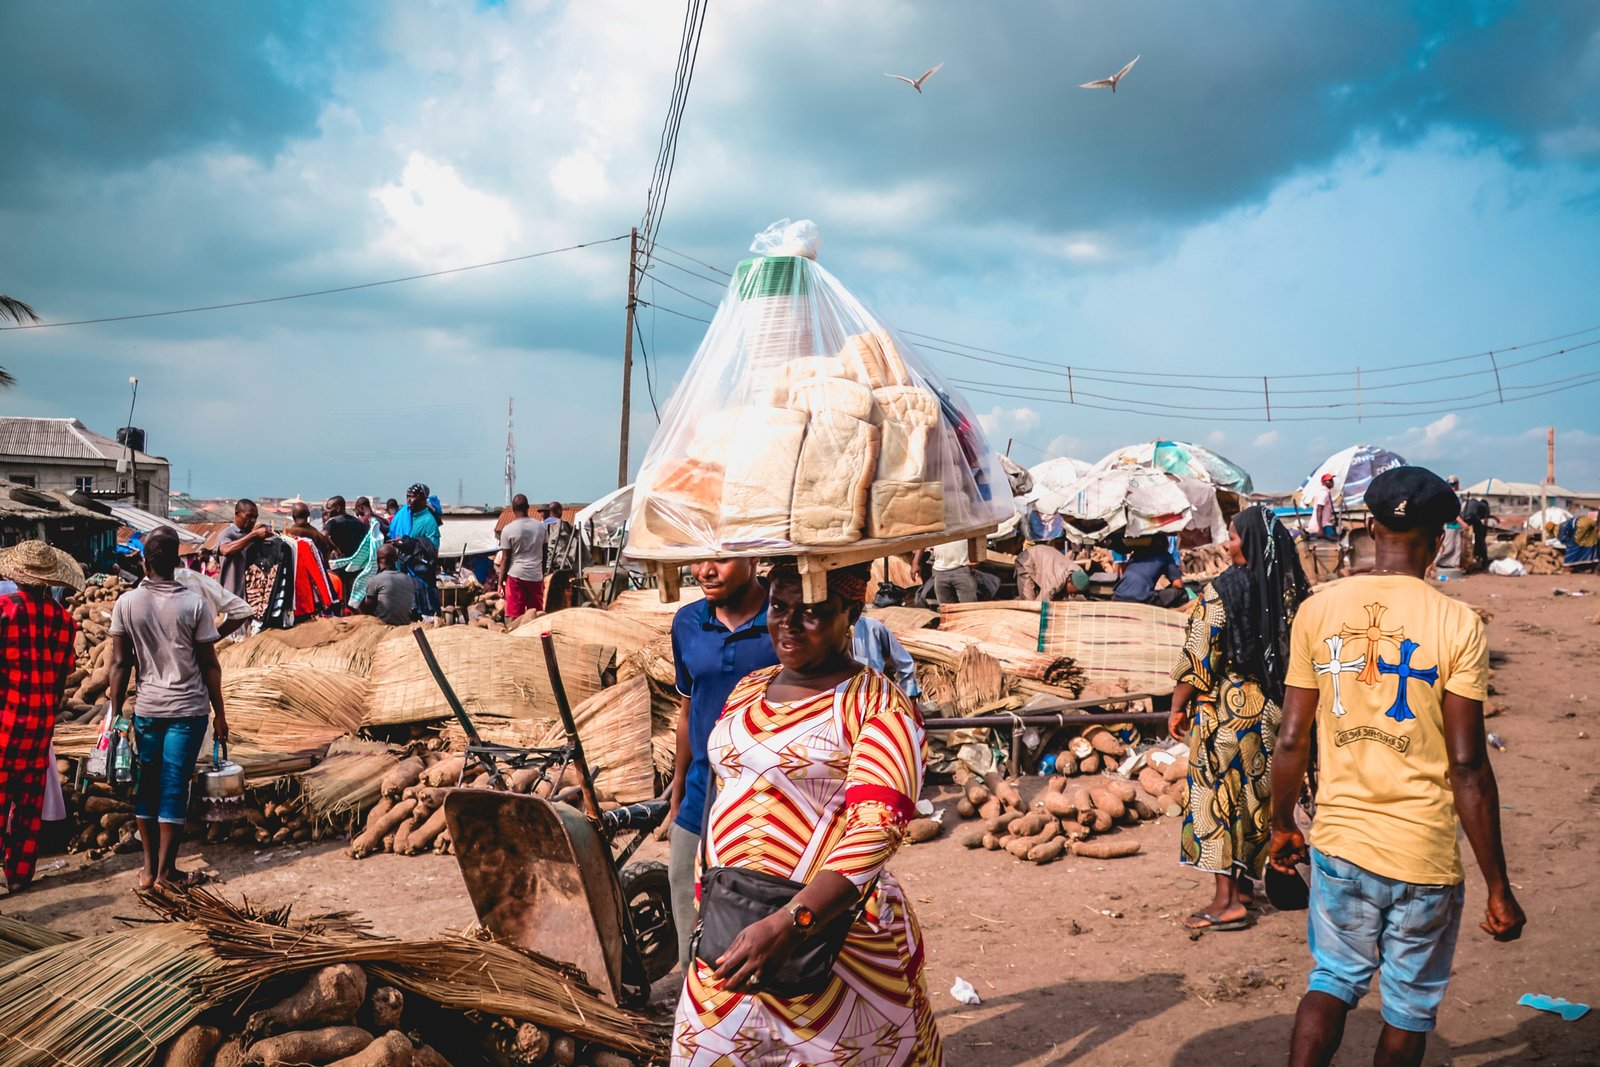
Opera spun the payments business out in 2018 with a Chinese founding team and a bet that Nigeria’s cash economy would move onto phones faster than its banks could build branches. The company grew through an agent network that turned kiosks and roadside stands into cash-in and cash-out points, and through services such as ride hailing and food delivery that brought customers into the app and kept them there. The rides were never the business. They were the distribution.
Precedent for the listing is thin. Jumia Technologies, the Berlin-based online retailer focused on Africa, listed on the New York Stock Exchange in 2019 and became the first Africa-focused technology company to do so; its share price has since fallen far below its debut level, and short sellers questioned its disclosures within months. OPay will be measured against that experience by investors who have learned to discount user counts in markets where verification is difficult.
The company’s own risk factors are unusually specific about the environment it operates in. Nigeria’s currency has been volatile, the central bank has changed rules on mobile money and lending disclosure more than once, and consumer credit in most African markets has a short history and shallow bureau data. OPay has grown quickly partly because it lends to customers whose repayment behaviour cannot be verified the way a bank in Chicago verifies it. That is a structural opportunity. It is also the reason credit losses are the line in the financials most likely to move when the cycle turns.
The macro backdrop is not neutral. The naira has lost much of its value against the dollar since 2023, which flatters dollar revenue reported from naira-denominated lending while making dollar-denominated costs harder to carry. Inflation has kept nominal loan yields high, and high nominal yields disguise credit losses that only appear when a borrower stops paying. In a market where a dollar of reported profit can be moved by an exchange rate, the quality of the loan book is the number analysts said they will spend the most time on.
Competitors are converging on the same pitch. Moniepoint and PalmPay are pursuing scale in Nigeria, MNT-Halan has moved toward a Cairo listing, and regional banks have begun buying their way into digital lending rather than building it. The distinction OPay offers is distribution: a network of agents and merchants that reaches customers beyond the salaried borrowers that traditional banks serve.
The open question is one the filing cannot answer. American investors have paid high multiples for payments companies whose revenue comes from taking a cut of transactions rather than from the interest and fees on money lent to consumers. OPay is now both. Whether the market prices it as a platform or as a lender will determine what the listing is worth, and the first test comes when the deal is priced rather than when it is filed. The filing, as the company itself notes, is a proposal and not a completed debut.



