John Felton, the chief financial officer of Amazon Web Services, gave an interview to Axios this week that read as an answer to a question investors have been asking for two years. “We recoup AI server investment costs within three years,” he said. “The demand is real.”
The number he put behind that claim was a backlog of nearly $500 billion as of the second quarter, the total of customer commitments not yet recognized as revenue. AWS reported $42.2 billion of revenue in that quarter, up 36.7 percent from a year earlier, and said its AI business had an annualized run rate above $25 billion, more than double the year-earlier figure.
Those results sit against a capital budget that has alarmed some shareholders. Amazon has said it expects about $220 billion of cash capital expenditure in 2026, most of it for AI capacity, and free cash flow has gone negative as the spending outruns depreciation. The shares have moved on capex guidance as much as on revenue.
The payback figure is aimed at a specific criticism. When a cloud provider buys a rack of accelerators, it books the cost as an asset and depreciates it over an assumed life, commonly five or six years. Bears argue that the useful life is shorter than that, because each generation of chips is faster and cheaper per unit of work, and because the buildings and the power contracts outlast the silicon inside them. If the true life is three years, the depreciation schedule overstates earnings.
Felton is making the argument in the opposite direction. A server that earns back its purchase price in three years is a server whose economics do not depend on the tail of its depreciation schedule. The remaining years are profit, even if the hardware is eventually written down early. On that arithmetic, a six-year schedule is conservative rather than aggressive.
The claim is not audited and the company has not published the cohort data behind it. What is observable is the backlog, and the backlog has been growing at a rate that is hard to attribute to a single customer. Felton described orders from large corporations, the biggest AI research labs and small and midsize businesses, which is the mix a cloud provider wants to report: the first group is sticky, the second is large and volatile, and the third is numerous.
The composition matters for a different reason. The AI labs that place the largest orders are themselves raising capital against future revenue, and a backlog that depends on their continued funding is a backlog with a financing condition attached. AWS’s answer is that the commitments are contractual and the deposits are real, which is true and does not settle what happens if a lab’s next round prices below its last one.
Gartner published a forecast this year that put more than $3.5 trillion of AI infrastructure investment at risk of impairment by the end of 2030, and predicted that more than 80 percent of AI-specialist cloud companies will not survive independently. That is not a forecast about AWS, which can fund its build from operating cash flow and rents capacity to the survivors. It is a forecast about the industry’s capacity, and it frames the question Felton was answering.
His second argument was about productivity, and it is the one that decides whether the demand lasts. He said an internal analysis found that token usage and output were almost directly proportional, and described AI as a tool for removing chores rather than a tool for cutting headcount. A customer that buys inference to do more work is a customer that keeps buying; a customer that buys it to shrink a payroll buys once.
There is a version of the bear case that Felton’s numbers do not address. If customers are buying capacity years in advance because they cannot get it otherwise, the backlog measures scarcity rather than demand, and scarcity is exactly what new supply destroys. The cloud providers are all adding capacity at the same time, and the first sign of a glut would be shorter contract terms rather than a smaller backlog.
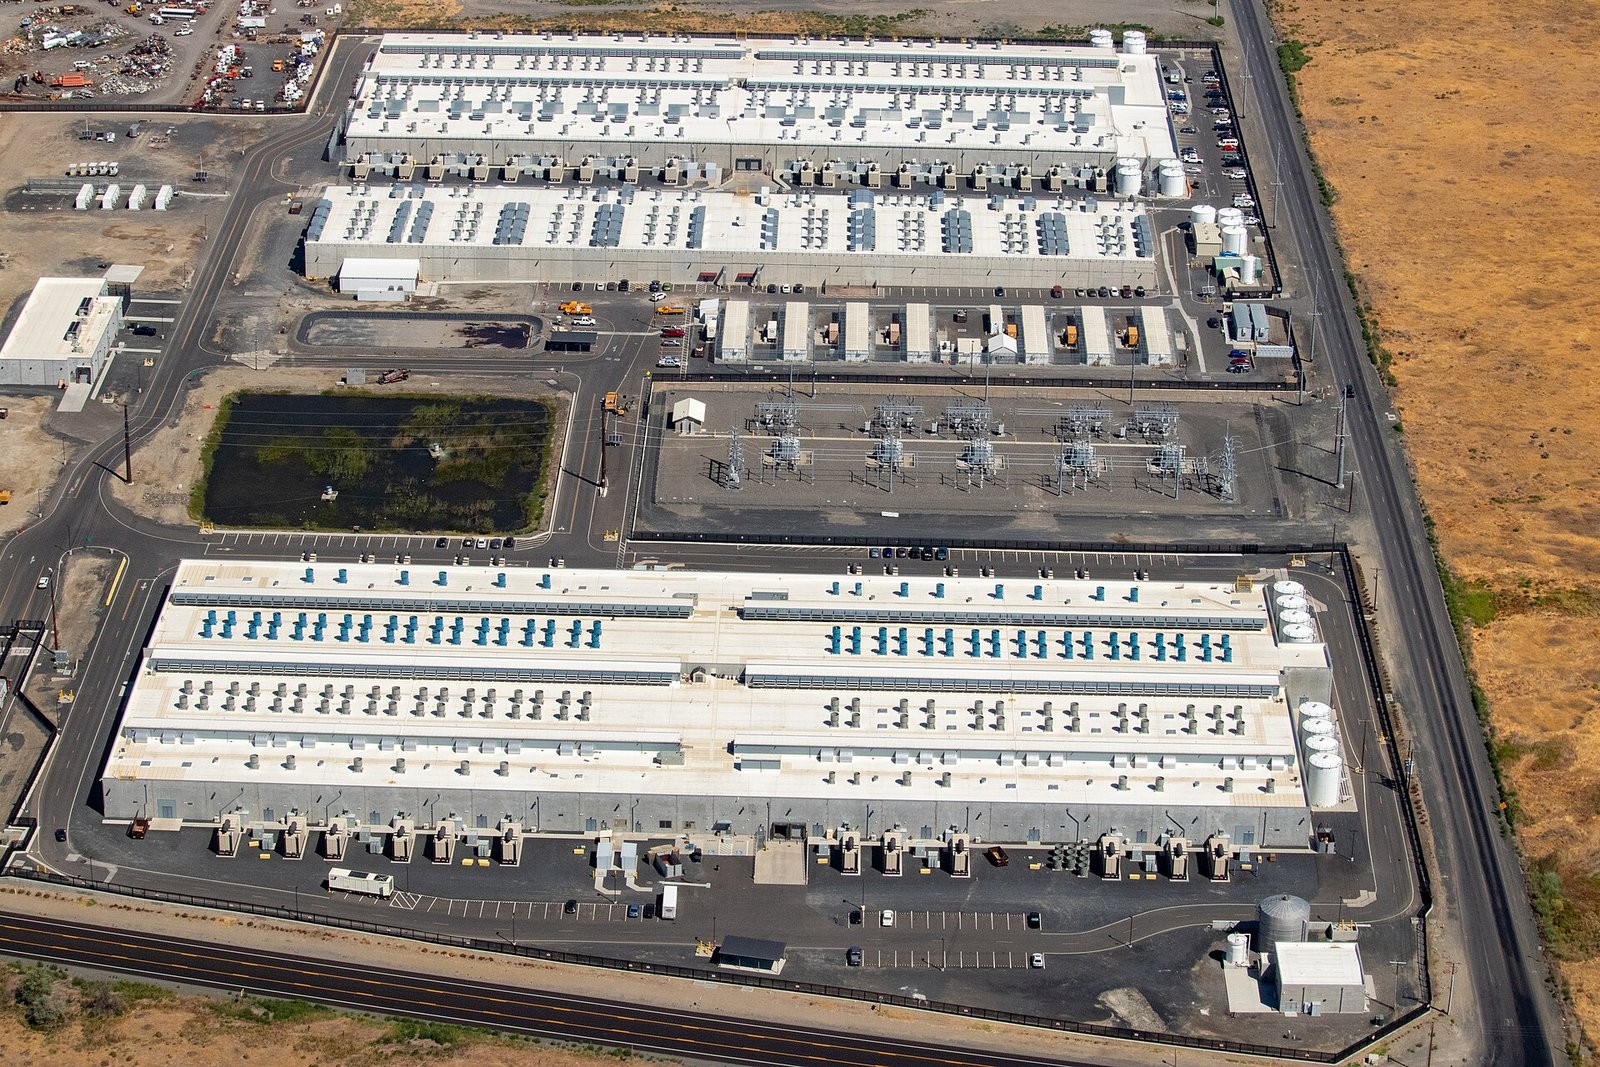
The capacity constraint is the counterweight to all of this. AWS, Microsoft and Google are all building against power and transformer lead times, and the shell of a data center can be finished before the substation that feeds it. A provider that cannot deliver capacity on schedule converts demand into a backlog it cannot bill, and the backlog figure that looks like strength becomes a measure of delay.
Analysts who cover the cloud said the number to watch is not the backlog but the capex guidance for 2027, and whether the payback assumption survives a hardware generation change. A three-year payback computed on today’s accelerator prices and today’s inference demand is a statement about the current cycle. The test comes when the next generation arrives and the current racks have to compete with it on cost per token.
For now the argument is holding. AWS accelerated for a fifth consecutive quarter, its AI revenue is compounding at a rate that justifies the buildings, and the executive making the case is the one who signs the depreciation schedule. Whether three years is the right number will be visible in the accounts, eventually, in the form of assets that stay in service longer than the skeptics expect.