
The document that reached the U.S. Securities and Exchange Commission on October 9 describes a company most American investors have never used and tens of millions of Nigerians use every day.
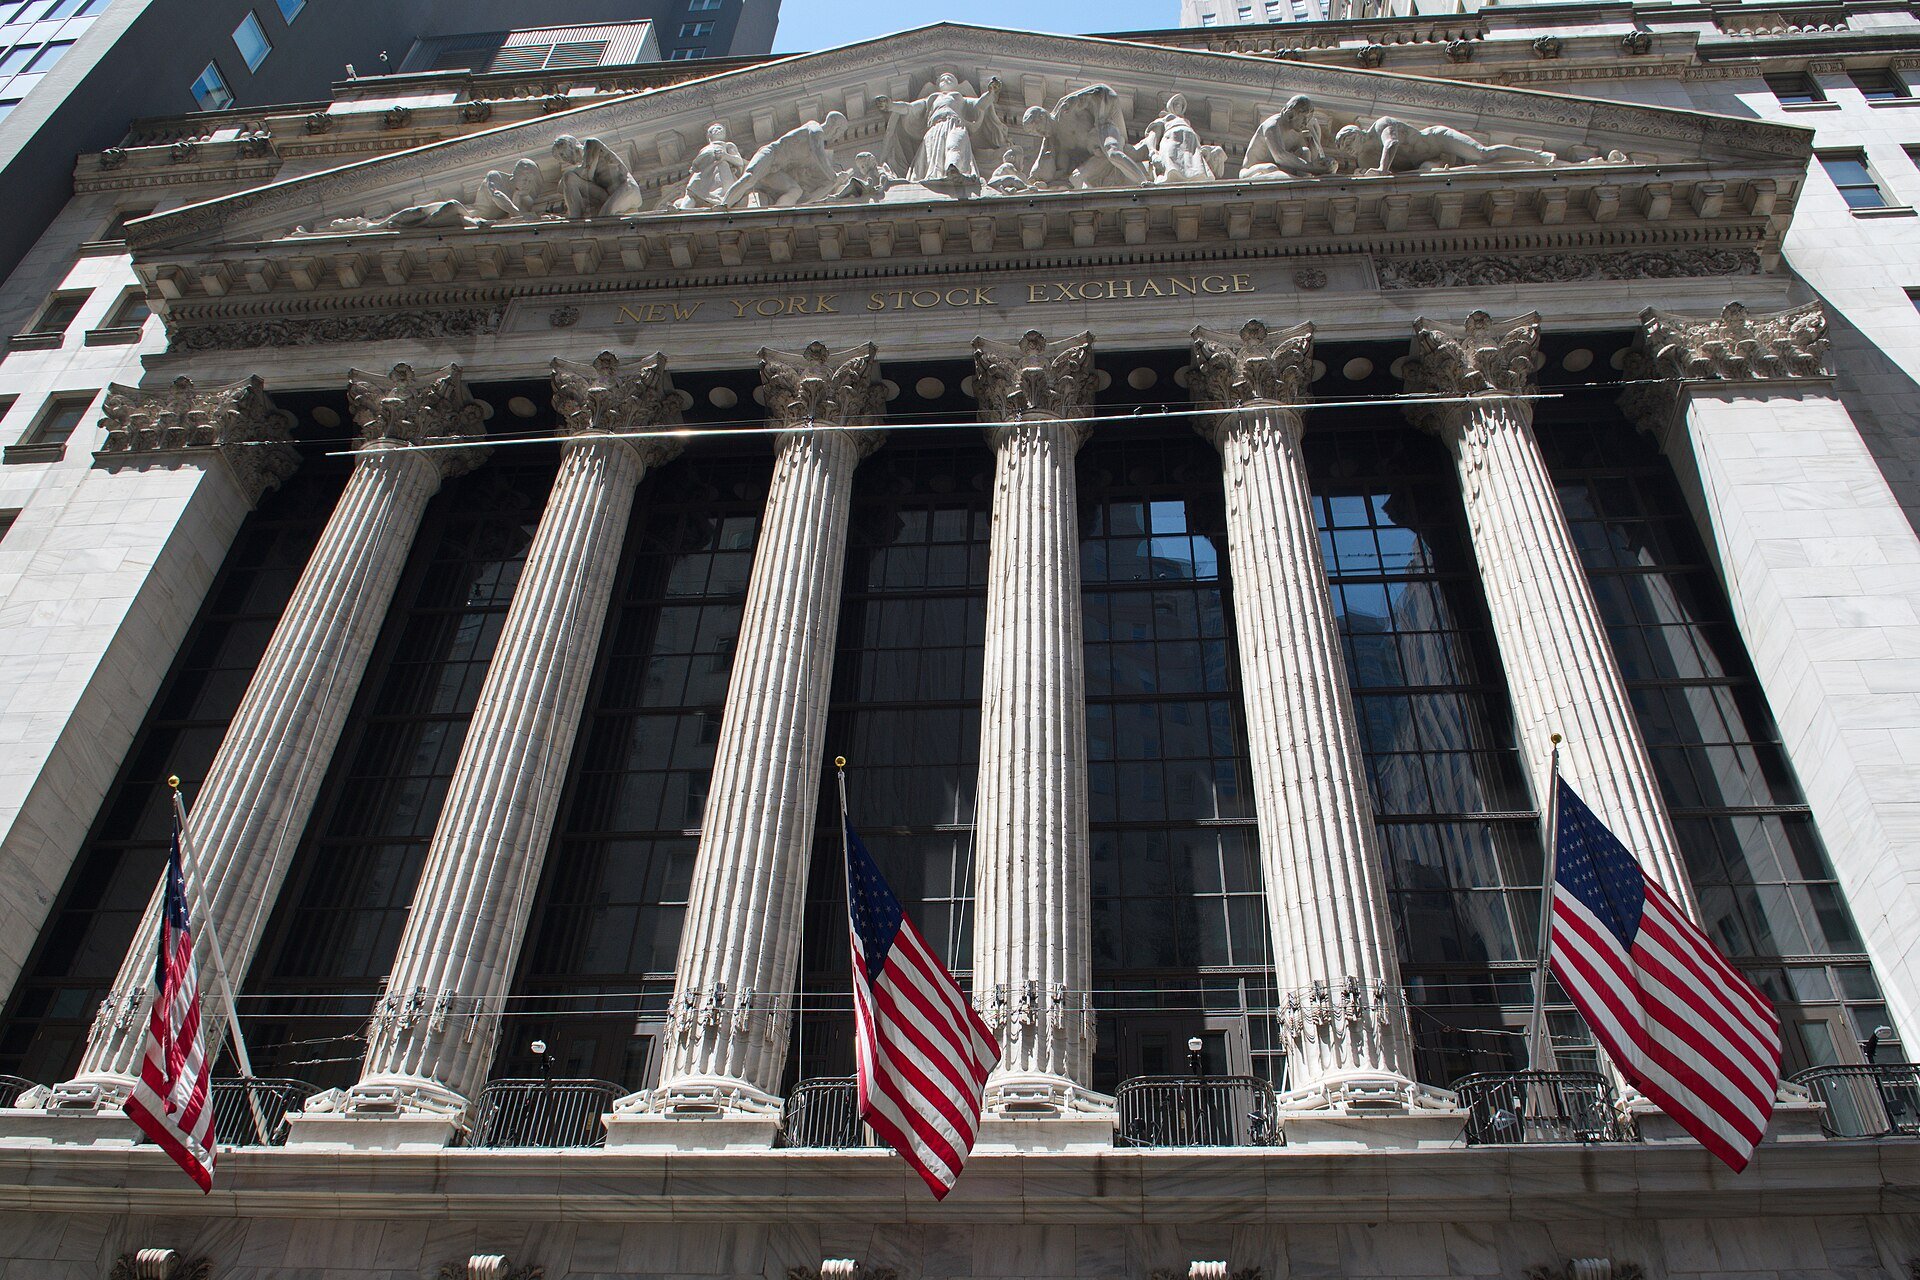
OPay, the Lagos-based app that began as a payments tool for a market where cash and agents outnumber bank branches, filed to list on the New York Stock Exchange under the ticker OPAY. The paperwork made public what the private company had never had to disclose: how it earns money, and how much of that money now comes from lending rather than moving it.
In the first half of 2026, loans OPay issues itself produced 50.6% of revenue, up from a minority share a year earlier, according to the filing. Payments, the business the company was built on, slipped to second place. Revenue for the six months reached $467.1 million, roughly 2.4 times the same period a year earlier, and net income was $90.9 million, more than four times the prior year.
Investors expect the offering to price in mid-November and have discussed a valuation near $4 billion, according to people familiar with the matter. OPay has not set a price range or said how much it intends to raise, and independent reports have put the target at up to $500 million. Standard Bank’s Africa arm has agreed to invest as much as $200 million, capped at a 4.99% stake after the listing, with its Africa head, Lungisa Fuzile, expected to join the board.
The scale beneath those figures is a story about small transactions. In the twelve months to June 30, 90.1 billion payments worth $558 billion passed through the platform, the filing shows. Divided out, the average transaction is about $6.19. That number explains the business better than any slogan: a bus fare, a phone top-up, a purchase at a roadside agent’s point-of-sale terminal.
Fifty and a half million people used OPay at least once a month as of July 31, and 26.8 million used it daily, up from 16.6 million monthly users in early 2024. The company is controlled by the Chinese billionaire Zhou Yahui and raised $570 million from investors led by SoftBank between 2018 and 2021. It first chased a super-app model, with motorbike taxis and food delivery, before narrowing back to financial services.
The concentration that comes with that growth is the part of the filing investors will weigh hardest. Nigeria produced 89.5% of first-half revenue, and the share has stayed near nine-tenths for two years. Almost everything OPay earns depends on one country’s currency, one regulator and one set of consumers whose spending is tied to the price of oil and the value of the naira.
The lending pivot carries its own arithmetic. OPay issued $927.6 million in new loans in Nigeria in the first half of 2026, and its expected credit loss provision rose to $118.4 million, the filing shows. Increasing a loan book is the fastest way to lift revenue in a market where most customers have no formal credit history. It is also the fastest way to discover how they behave when incomes fall.
Analysts who follow African fintech note the symmetry. Payments produce thin, reliable margins and enormous volume. Lending produces wider margins and a loss rate that only shows up after a downturn. OPay has moved toward the second model at the point where its home market is under pressure from inflation and a weaker currency, which raises the risk that a macroeconomic shock and a credit shock arrive together.
The precedent cuts both ways. Jumia, an earlier African company to list in New York, drew attention and then a long period of doubt, and its shares never matched the reception that greeted the offering. OPay would be the first fintech with mostly Nigerian customers to sell shares in the U.S., which gives it a scarcity value and a scarcity problem: few comparable companies exist to anchor the price.
The filing also lists risks that put the company’s reliance on third parties on the record. OPay depends on independent agents to open accounts, issue cards, install terminals and handle deposits, and it warns that poor service by those agents could damage the business. Regulators require identity checks on wallets, and the company flags its exposure to rules that could tighten.
The secondary listing OPay plans in Lagos adds a wrinkle. The filing cautions that shares traded in Nigeria may not be swappable for those traded in New York, which leaves two prices for one company and a question about which one a global investor should trust.
What the offering tests is whether investors will pay a developed-market multiple for an emerging-market lender whose customers make six-dollar payments and whose credit history is being written in real time. OPay has the growth story. The filing lays out, for the first time, the concentration and credit risk that comes with it, in the same document.
The company has not said when it will price. When it does, the market will be asked to decide whether a loan book on top of a payment network is worth more than a payment network on its own, and whether one country is enough of a market to build a public company on.



