For most of the past decade, the profit in computing accrued to the companies that designed the systems and wrote the software. In the three months that ended in September, a different group collected it.
Nikkei Asia reported early on Oct. 31 that the combined operating profit and the combined net profit of the world’s five largest memory-chip suppliers each exceeded the equivalent figures for five of America’s largest technology companies over the same quarter. It was the first time on record that both measures cleared that bar at once, according to the report.
The comparison is crude by construction. The five memory makers — Samsung Electronics, SK Hynix, Micron Technology, Kioxia and SanDisk — do not share a fiscal calendar, and adding operating profit across companies that depreciate fabs on different schedules and value inventory on different assumptions produces an approximation rather than a fact. The direction, though, is not in dispute. Contract prices for DRAM and NAND flash have risen for four consecutive quarters, and the companies that etch those chips have converted the increase into margin at a rate the industry has not managed since the last shortage.
Samsung, the largest of the group by revenue, and Kioxia, the NAND specialist carved out of Toshiba, were the clearest beneficiaries of the repricing, according to the Nikkei report.
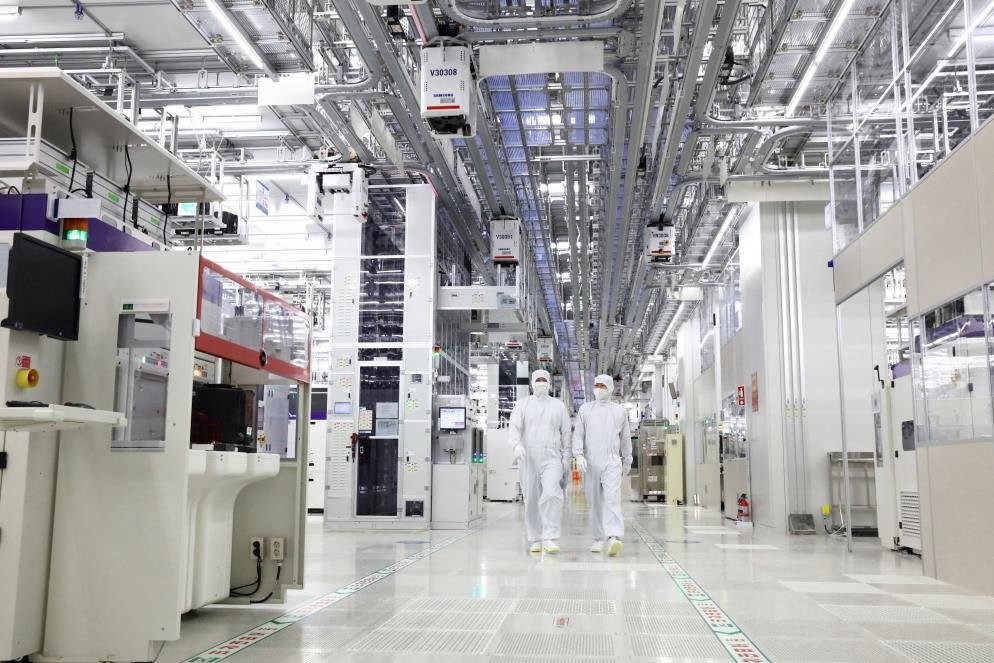
The mechanism is not mysterious. Memory is a commodity sold on contract, and its price is set at the margin by the balance between wafer capacity and demand. Over the past two years the artificial-intelligence buildout has absorbed a growing share of leading-edge capacity for high-bandwidth memory, the stacked DRAM that sits beside an accelerator and feeds it data. HBM consumes several times the wafer area of conventional DRAM for the same number of bits, and it yields less. Every wafer converted to HBM is a wafer not making the memory that goes into a laptop, a phone or a plain server.
That conversion tightened the market for ordinary memory just as server builders began ordering more of it. The result has been a seller’s market in a business that spent most of the previous decade as a buyer’s one.
Investors have started to ask how long it lasts. The support for pricing, as the Nikkei report noted, comes from a shortage rather than from a change in the structure of demand, and every producer with a balance sheet is now planning to add capacity.
Memory has a long record of punishing the companies that mistime it. Micron and SK Hynix both reported operating losses in 2023, when a glut pushed prices below cash cost for parts of the year, and the recovery that followed was equally violent in the other direction. What makes the current quarter unusual is not that memory is profitable. It is that memory is more profitable, on these measures, than the customers buying it.
New capacity does not arrive on demand. A fab takes two to three years from announcement to volume production, and the industry’s expansion plans, taken together, land in a cluster rather than smoothly. If the additions now being financed come online while prices are still near their peak, the same arithmetic that produced this quarter’s record will run in reverse.
The demand side has not yet given a reason to expect that. The largest cloud operators have raised capital budgets repeatedly this year, and each generation of accelerator carries more memory, not less. Memory has moved from a cost to be negotiated down to a component to be secured, which changes how buyers behave: they sign earlier, they accept less favorable terms, and they pay for certainty.
There is also a limit, and it is beginning to show. Memory is a large enough share of the bill of materials for a personal computer or a phone that sustained increases reach the consumer. Intel’s chief executive said on Oct. 30 that customers had begun slowing PC purchases in part because of memory prices, a sign that the shortage is now visible in end demand rather than only in supplier income.
For the technology giants on the other side of the comparison, the pressure runs through a different line on the income statement. Their profits are being consumed by depreciation on data centers they are still building and by the operating costs of running them. The memory makers carry the opposite burden: less capital intensity per dollar of current revenue, and a product that is scarce.
Both conditions are, in principle, temporary. Only one of them arrives on a schedule. Depreciation is contractual. Scarcity lasts until someone builds enough capacity to end it, and the companies earning record profits today are the ones financing that capacity.
Memory earnings are volatile in both directions, which is why the stocks trade at low multiples even in good years. The five American companies in the comparison earn across search, advertising, software subscriptions and cloud contracts, businesses with more durable revenue. A quarter in which the chipmakers win the profit comparison is a quarter in which the cyclical part of the industry is at the top of its range.
Analysts who follow the sector make a narrower point. Contract prices for the first half of next year are being negotiated now, and the suppliers have more visibility into that book than they had at any point since 2022. Visibility is not the same as permanence. It means the next two quarters are largely sold, at prices that will look generous if capacity stays tight and embarrassing if it does not.
For the five suppliers, the record is a statement about the present rather than about a new equilibrium. The question circulating among investors is not whether memory can earn this much in a good quarter. It is how much of the next two years has already been committed, at what price, and who is left holding the capacity when the shortage ends.