The largest single check ever written to a quantum computing company was not from a specialist fund. It came from a group of mainstream investors that included names better known for chips, banking and sovereign wealth than for qubits.
That detail, tucked into PitchBook’s latest tally of the sector, captures how quickly money has changed its mind about a technology that spent years on the edge of commercial relevance. Venture investors have put more than $4 billion into quantum computing companies so far this year, according to PitchBook data cited by the Financial Times on September 26 — a figure approaching the total for all of 2025, which itself nearly matched the combined amount raised in the previous four years.
The acceleration is steep even by the standards of a frothy AI cycle. In 2025, quantum startups raised a record $3.9 billion across 127 deals, according to PitchBook, the highest annual total on record. The capital has also shifted in character. Venture-growth investment jumped from roughly 1 percent of deal value in 2024 to 27.5 percent in 2025, as late-stage rounds came to dominate the field.
Quantinuum set the pace. In November 2025, the company closed an $838.9 million Series B at a $10 billion pre-money valuation, the largest quantum deal on record. PsiQuantum raised $1 billion at a $6 billion pre-money valuation in September. The first quarter of this year delivered four exits worth $5.7 billion in liquidity, roughly 15 times the combined total of the prior three years, and a record 60 venture deals.
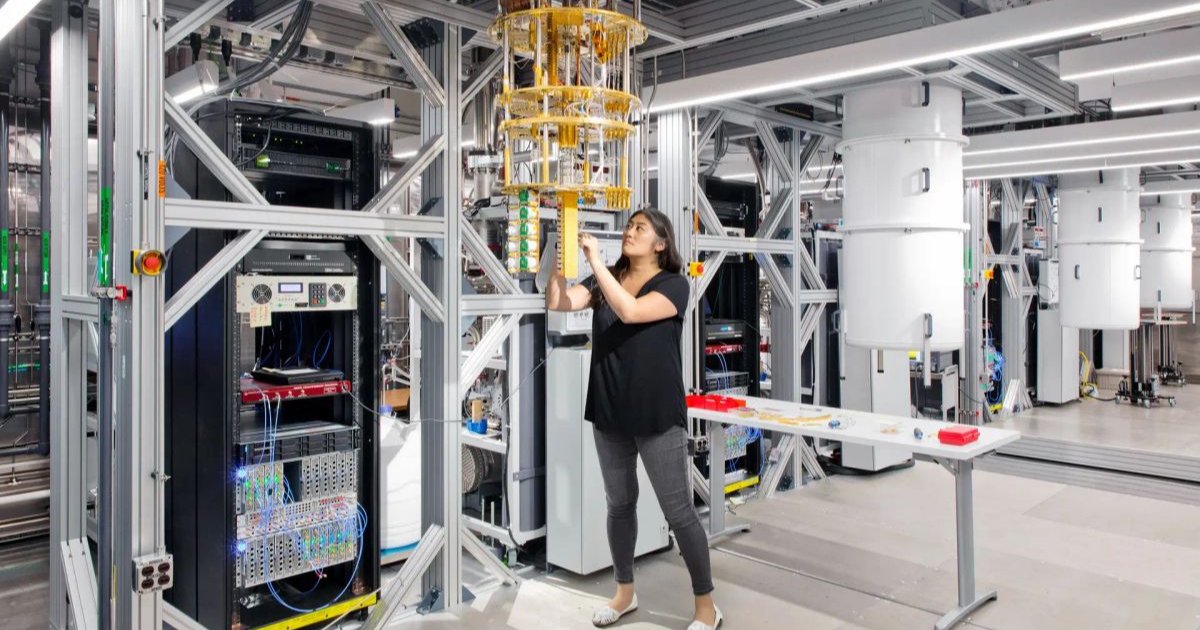
The companies behind those numbers are building different kinds of machines. Quantinuum, formed from Honeywell’s quantum unit and Cambridge Quantum Computing, works on trapped-ion hardware. PsiQuantum is developing photonic computers built on silicon. Their backers are betting that one of these approaches, or several at once, will eventually deliver a machine that does work no ordinary computer can.
The sector has been here before. After an early rush of enthusiasm, venture funding corrected in 2023, and a number of startups folded or were absorbed into larger rivals. The current wave is different in scale, and its backers argue it is different in substance, because the hardware has begun to move from laboratory demonstrations toward commercial machines.
The roster of backers tells its own story. NVIDIA, BlackRock, JPMorgan and a number of sovereign wealth funds now lead the largest rounds, displacing the small group of specialist quantum venture firms that once carried the sector almost by themselves. Median post-money valuations have climbed sharply as a result.
Analysts said the money is arriving faster than the machines. Quantum computers today can perform certain narrow tasks, but a general-purpose machine capable of the code-breaking and simulation work the field promises remains years away, and the gap between the capital pouring in and the revenue coming out is wide by the standards of most venture categories.
Some of that spending is already turning into small but real contracts. Pharmaceutical companies rent time on quantum machines to model molecules, banks experiment with portfolio optimization, and defense agencies test the hardware for materials and code work. The revenue from such pilots is modest next to the capital arriving, but it gives investors a signal that the technology is moving from the laboratory toward paying customers.
The enthusiasm is driven less by current earnings than by two convictions. The first is that quantum will one day sit alongside AI as a foundational technology, with uses in cryptography, materials science and the simulation of chemical reactions. The second is a geopolitical urgency to be first, as governments compete to own the next leap in computing.
Part of the urgency is defensive. Advances in quantum computing are expected, eventually, to threaten the encryption that protects everything from banking to state secrets, and governments and large institutions are spending ahead of that risk rather than behind it.
That public money still dominates. Governments in more than a dozen countries have built national quantum programs, and the largest share of total quantum investment flows from state funds rather than venture capital. The private round that just closed is, in that sense, riding a wave that governments started.
The result is a market in which a company’s promise, not its profit, sets the price. Startups that have never shipped a broadly useful machine now trade at valuations once reserved for mature software companies, and the investors who fund them are betting that the technical advances will land before the patience runs out.
PitchBook’s own researchers frame the moment as a compression of the usual cycle. Funding that once arrived in measured stages is now arriving all at once, as hardware advances, intensifying competition and a surge of institutional money pull the timelines forward.
For the companies, the windfall is a chance to lengthen their runway at exactly the moment the engineering gets hard. For the investors, it is a bet on a field that has burned through decades and billions on the way to a working machine — and has never been closer to proving the bet either right or wrong.