The distance between what a company asks for and what buyers will pay is usually negotiated in private, across a table, with a banker in the room. For Nscale it is being negotiated in public, one anonymous quote at a time.
The company is seeking a valuation of about 30 billion dollars in its American initial public offering, according to Bloomberg, which reported on October 18 that some investors have told the underwriters a figure between 16 billion and 19 billion dollars is closer to reality. The low end of that range is 47 percent below the target.
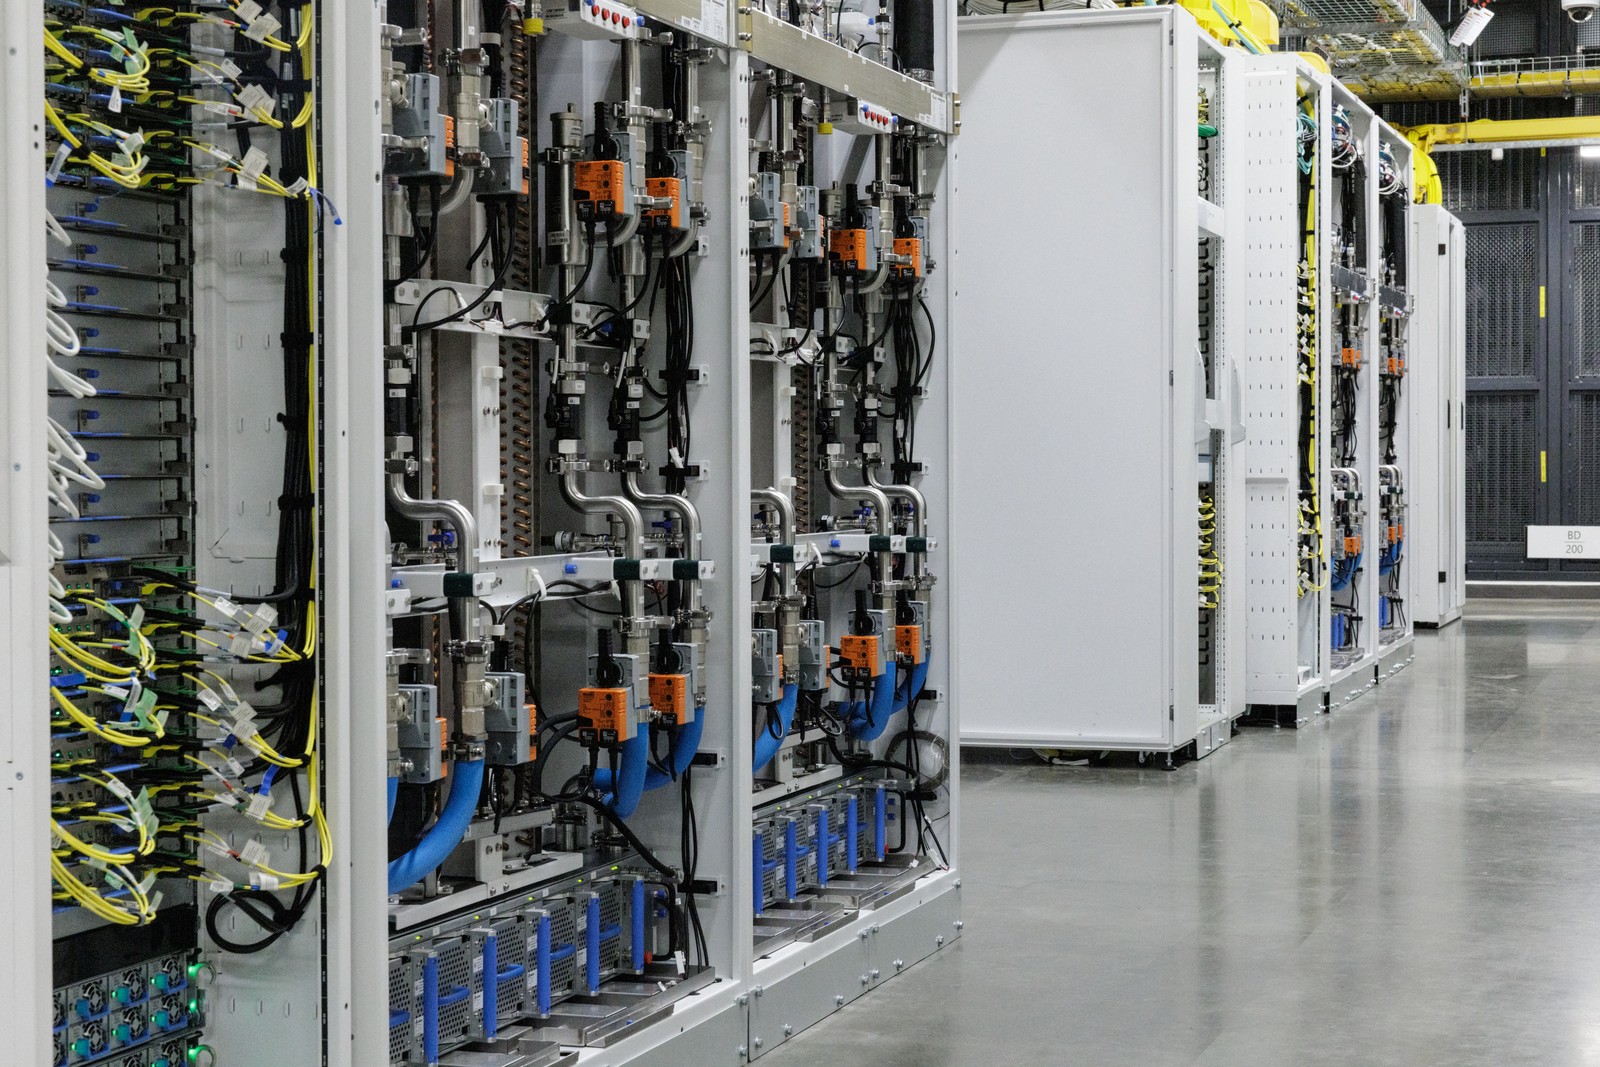
Nscale is a London-based developer of artificial intelligence data centers, backed by Nvidia, and its growth has been the kind that invites both enthusiasm and arithmetic. Contracted value has risen from 100 million dollars to more than 103 billion dollars in about two and a half years, and it has raised 3.36 billion dollars along the way. Its filing names Microsoft and Anthropic, two of the largest buyers of computing in the world, as the customers expected to provide most of its revenue.
The pushback has a backdrop, and it is not company-specific. Firmus, an Australian developer of AI data centers, saw its listing plan fail, an outcome that gave investors a recent example of what happens when these businesses meet a public market. Shares of listed computing landlords have fallen sharply from their highs, and the credit market has repriced the sector’s debt to levels that imply distress for the weakest borrowers.
Then came Sunday’s announcement. Microsoft, which is both an investor in Nscale and a customer, said it had ended an agreement covering a data center project in Britain. The site is in Loughton, in Essex, northeast of London, where grid officials told the developer they did not expect to deliver power until the 2030s, according to a report in the Telegraph.
One site is not a business, and Nscale has said its relationship with Microsoft is intact and its other contracts unaffected. But a prospectus is read as a document about concentration, and the withdrawal arrived in the same month the shares were meant to be marketed. Investors who underwrite contracted revenue want to know how easily a contract can end.
The valuation gap is easier to see in ratios than in adjectives. At 30 billion dollars against 103 billion dollars of contracted value, the company is asking roughly 29 cents for each dollar of backlog. At 19 billion dollars the figure is about 18 cents, and at 16 billion about 16 cents. What a buyer pays for backlog depends entirely on the margin inside the contracts and the capital required to deliver them.
That is where the disagreement sits. A contract to supply computing for a decade is an asset, and a contract signed in a period of scarce capacity may carry a price that looks generous in 2028, when several million graphics processors are scheduled to come online. The cost of building the halls, connecting them to a grid and financing the equipment in between is where the margin goes.
Power has become the variable that decides schedules. For most of the past three years the binding constraint on AI capacity was the supply of accelerators. It has been migrating toward interconnection queues, transformers and local opposition, none of which respond to capital on the timetable the industry works to. A project without an energization date is a building with good cooling.
For Nscale specifically, the geography compounds the problem. Britain has spent two years courting American computing investment and has the land, the fiber routes and the customers. What the London region lacks is the ability to connect very large electrical loads quickly, and a company whose growth story is measured in contracted gigawatts is exposed to that constraint in a way that a software business is not.
The process has its own signals. Nscale has not begun its formal roadshow, and it is working through comments from the Securities and Exchange Commission on its filing. A company that expected to be pricing shares in October is spending the month answering accounting questions instead, and delay in a falling market tends to cost more than the questions did.
A print at 16 to 19 billion dollars would travel beyond the company. Private developers that raised at higher marks would face questions from their own investors about the last round’s price. Lenders who accepted contracted value as collateral would revisit the loan-to-value assumptions behind those facilities. Public comparables would set the reference, and the reference would be lower.
The counterargument is not weak. Contracted revenue from investment-grade customers is a different asset from a forecast, Nvidia’s backing carries weight with the suppliers that allocate equipment, and Microsoft’s other agreements with the company remain in place. A market that has overshot on the downside can produce a discount that says more about sentiment than about delivery.
But sentiment is what an offering prices. The book is built from orders, and orders arrive at a level. If the level is half the target, the company faces a choice between accepting a lower mark and withdrawing, and both outcomes are informative for a sector that has spent two years converting announcements into valuations.
The interesting question is not where Nscale prices. It is what the company does if the answer stays at half. Withdrawing preserves the private mark and delays the reckoning. Pricing lower raises the money and resets every comparable in the sector, which is a public service performed at the seller’s expense.
Either way, the gap between 30 billion dollars and 19 billion dollars is now a published number. That is what a roadshow does before it sells anything: it discovers, in public, what the last private round was worth.