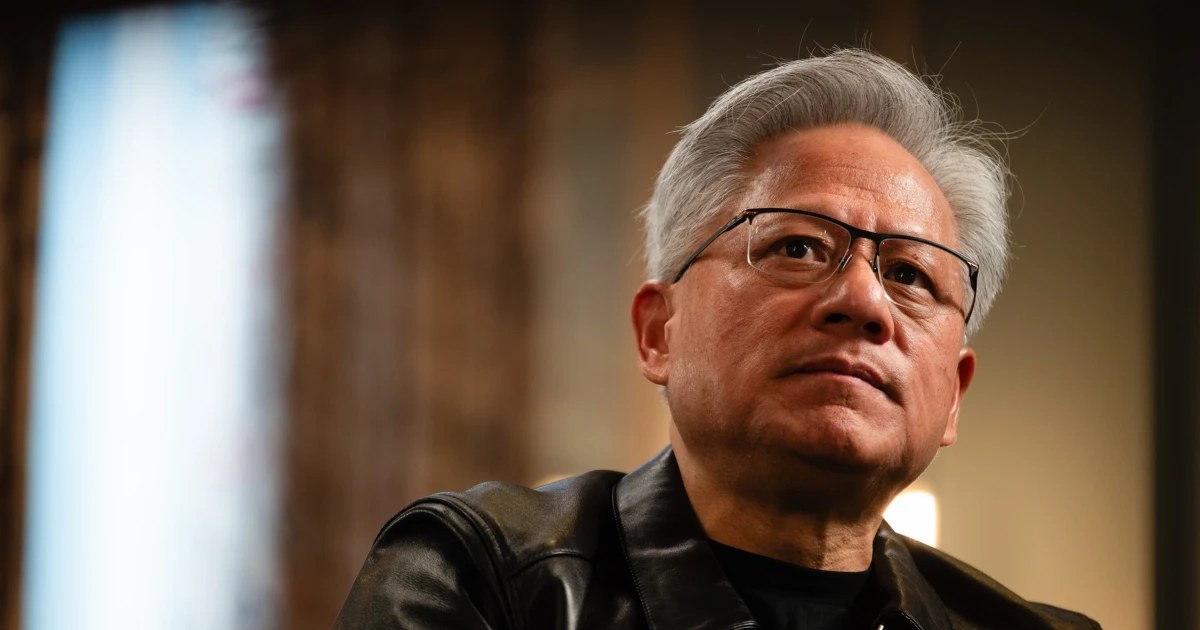
Nvidia’s independent directors have retained Joon H. Kim, a former acting U.S. attorney for the Southern District of New York, and his firm, Wachtell, Lipton, Rosen & Katz, to conduct an investigation tied to reports about chief executive Jensen Huang’s personal conduct.
The board disclosed the move in a statement on Nov. 10. The scope covers corporate governance and disclosure, and the work is supervised by a committee of independent directors with the assistance of outside independent counsel. The statement did not describe any allegation of financial misconduct, and it did not say what the investigation had found, because it has not finished.
The probe was announced two days earlier, on Nov. 8. The same day, Huang wrote to employees acknowledging that he had been unfaithful to his wife, saying he took full responsibility and accepted the criticism that followed. Reports about the relationship had circulated before the letter, and the letter did not dispute them.
The distinction between the personal conduct and the corporate inquiry is the part worth understanding. A chief executive’s marriage is not a matter for a board committee. The question a board can investigate is what it knew, when it knew it, and whether anything the company said publicly or filed with regulators was affected by what it did not know. That is why the announced scope reads the way it does, and why the firm hired is the one that governments and boards call when a disclosure question is likely to end up in front of a regulator.
Kim spent years as a federal prosecutor in Manhattan, a district that handles a disproportionate share of securities and corporate cases. Wachtell has built its practice on advising boards through crises rather than on defending companies against them. Hiring both signals that the board expects its work to be reviewed by someone outside the company, whether that is the Securities and Exchange Commission or a plaintiffs’ lawyer with a subpoena.
The political dimension arrived within a day. Senator Kevin Cramer, a Republican, publicly called on Huang to resign on Nov. 11, arguing that the episode weakens the company’s credibility in Washington. That is not a legal argument and it is not a small one. Nvidia’s business depends on export licensing decisions made by officials who take meetings with its chief executive, and the company has spent three years arguing with both Washington and Beijing about which chips can be sold where.
A chief executive who is the company’s principal negotiator with governments is a different asset from a chief executive who runs operations. The first kind is difficult to replace and difficult to bench. The second can step aside for a quarter while an investigation runs. Nvidia’s board said Huang continues in his duties during the inquiry, which is the standard formulation and also the only one available to a company whose strategy is built around one person’s relationships.
Boards rarely remove founders, and they almost never do so over a matter that does not involve company funds. The precedents that exist mostly involve conduct that either broke a law or impaired the company’s ability to operate. Cramer’s letter is an attempt to establish the second condition before the investigation establishes anything, and the board’s statement is an attempt to keep the question inside a process it controls.
The market has been through this before with large technology companies and has generally treated governance questions as noise until they touch revenue. Nvidia is one of the most valuable companies in the world, and its shares have absorbed export restrictions, supply constraints and antitrust scrutiny without a lasting repricing. A board investigation with an undefined timeline is unlikely to be the event that changes that, unless it produces a finding that forces a disclosure the company would rather not make.
The harder question is succession. Nvidia has never named an heir, and its bench of publicly known executives is thin relative to its size. A company that has been built around a founder’s technical judgment and his willingness to make large, early bets does not have a second person who can make them. Every board in that position knows the risk and has chosen to live with it, because the alternative is to plan for the departure of the person creating the value.
Timing matters for a different reason. The investigation will run alongside a quarterly report, customer commitments that stretch years out, and a policy calendar in Washington that does not wait for outside counsel. If the committee finishes before the next earnings call, the company will have to decide how much to say. If it finishes after, the questions will be asked anyway and the answers will be that the process is ongoing.
Employees will read the statement for signals about how the company is being run. Investors will read it for signals about disclosure risk. Both will notice that the board chose a prosecutor rather than a compensation consultant, which tells you what kind of exposure it thinks it has.
The question left open is whether the board is investigating the relationship itself or the sequence of what was known and what was said about it. Those are different inquiries with different consequences, and the statement released this week does not say which one this is.