
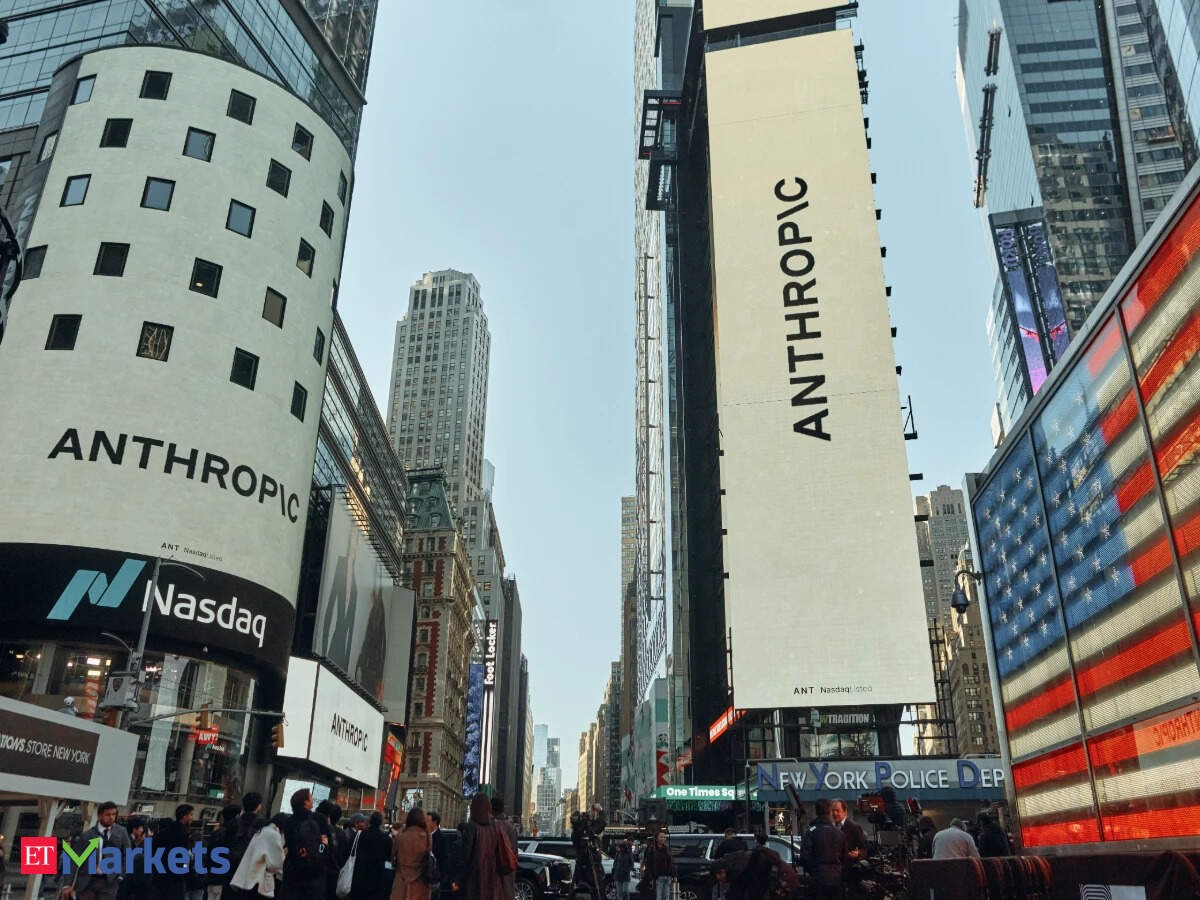
Anthropic raised $107.3 billion in the largest initial public offering ever completed, pricing shares at $83 and valuing the company at roughly $1.5 trillion on a fully diluted basis. Orders ran many times the size of the book, and almost none of that demand was filled.
The deal exceeds SpaceX’s listing and makes Anthropic the first US public company whose main product is a frontier artificial intelligence model rather than software built on someone else’s. There is no template for pricing that kind of company, which is part of why the fight over shares turned so sharp.
About 1,200 institutions placed orders. More than half of them received nothing at all, according to people familiar with the matter, and orders from European accounts were almost entirely ignored, including orders from funds that had held the stock through earlier private rounds.
The tilt was a decision by the underwriters rather than a shortage of paperwork. US long-only managers and existing holders were weighted on the argument that they hold through volatility, while fast money that would have sold into the first print was pushed to the back of the queue.
Relationship counted for more than the size of the order, according to people who saw the allocation lists. Early backers were treated as long-term holders and given stock, while late arrivals with large indications and no history were told to buy in the market instead.
Two venture firms sit at the top of the register. Lightspeed Venture Partners and Iconiq Capital each hold close to 2% of the company, stakes worth more than $25 billion at the offer price and worth more than every bank on the deal will collect in fees.
Sound Ventures holds about 0.5%. Factorial Funds committed $565 million and carries a paper gain of roughly 19 times on it, one of the better outcomes in a book that went mostly to buyers with no relationship to the company and no intention of selling.
Novelty cuts both ways for the buyers who did get shares. There is no long record of quarterly numbers to anchor an $83 price, the customer base is concentrated in a few dozen large enterprises, and the closest listed comparables are either private or far smaller than this.
Only a slice of the equity trades. Founders, employees and early investors sit behind lockups, so the first weeks of pricing will be set by a thin float and by a handful of holders who can move the tape with a single order.
Index funds will be forced buyers at some point, because the company’s size makes inclusion in the main benchmarks close to automatic once the float clears the threshold. The timing depends on rules that index providers have never applied to a listing of this scale, and a larger float would also give short sellers room to build positions without borrowing stock at punishing rates.
Underwriters sold scarcity: a short list of listed companies that own a frontier model outright, and customers who pay monthly for access instead of buying hardware once. That argument carries furthest when nothing else on the shelf looks remotely similar, and scarcity does the work that a dividend yield does in older parts of the market.
The counterargument is capacity. Revenue depends on rented compute, compute is priced by vendors whose chips the company competes against in the eyes of some investors, and gross margin is therefore a moving number rather than a fixed one. Capacity contracts with cloud providers set the price, and those contracts reprice.
Regulation adds a second variable. Export rules, procurement reviews and the treatment of model weights in Washington all reach the top line, and none of them was folded into an $83 price set in a single afternoon. Reviews of procurement and of foreign customers add lead time that a fast-growing company does not have.
What would justify the valuation is retention. Enterprise contracts that renew, seats that expand inside existing accounts and pricing that holds as cheaper models arrive are the three numbers analysts say they will check before they touch their models. Gross margin, once reported quarterly, will decide whether $1.5 trillion was a clearing price or a ceiling.
That test arrives on a schedule. The first quarterly report sets the tone, the lockup calendar supplies the supply, and the institutions that received nothing will decide whether to buy in the market or wait for a better entry. A first report that misses on any of them hands the doubters a valuation argument that has nothing to do with the model.
For now the number that matters is $107.3 billion, and the second is zero, which is what more than half of the buyers who asked for stock were given. The distance between those two figures is the deal’s real legacy.



