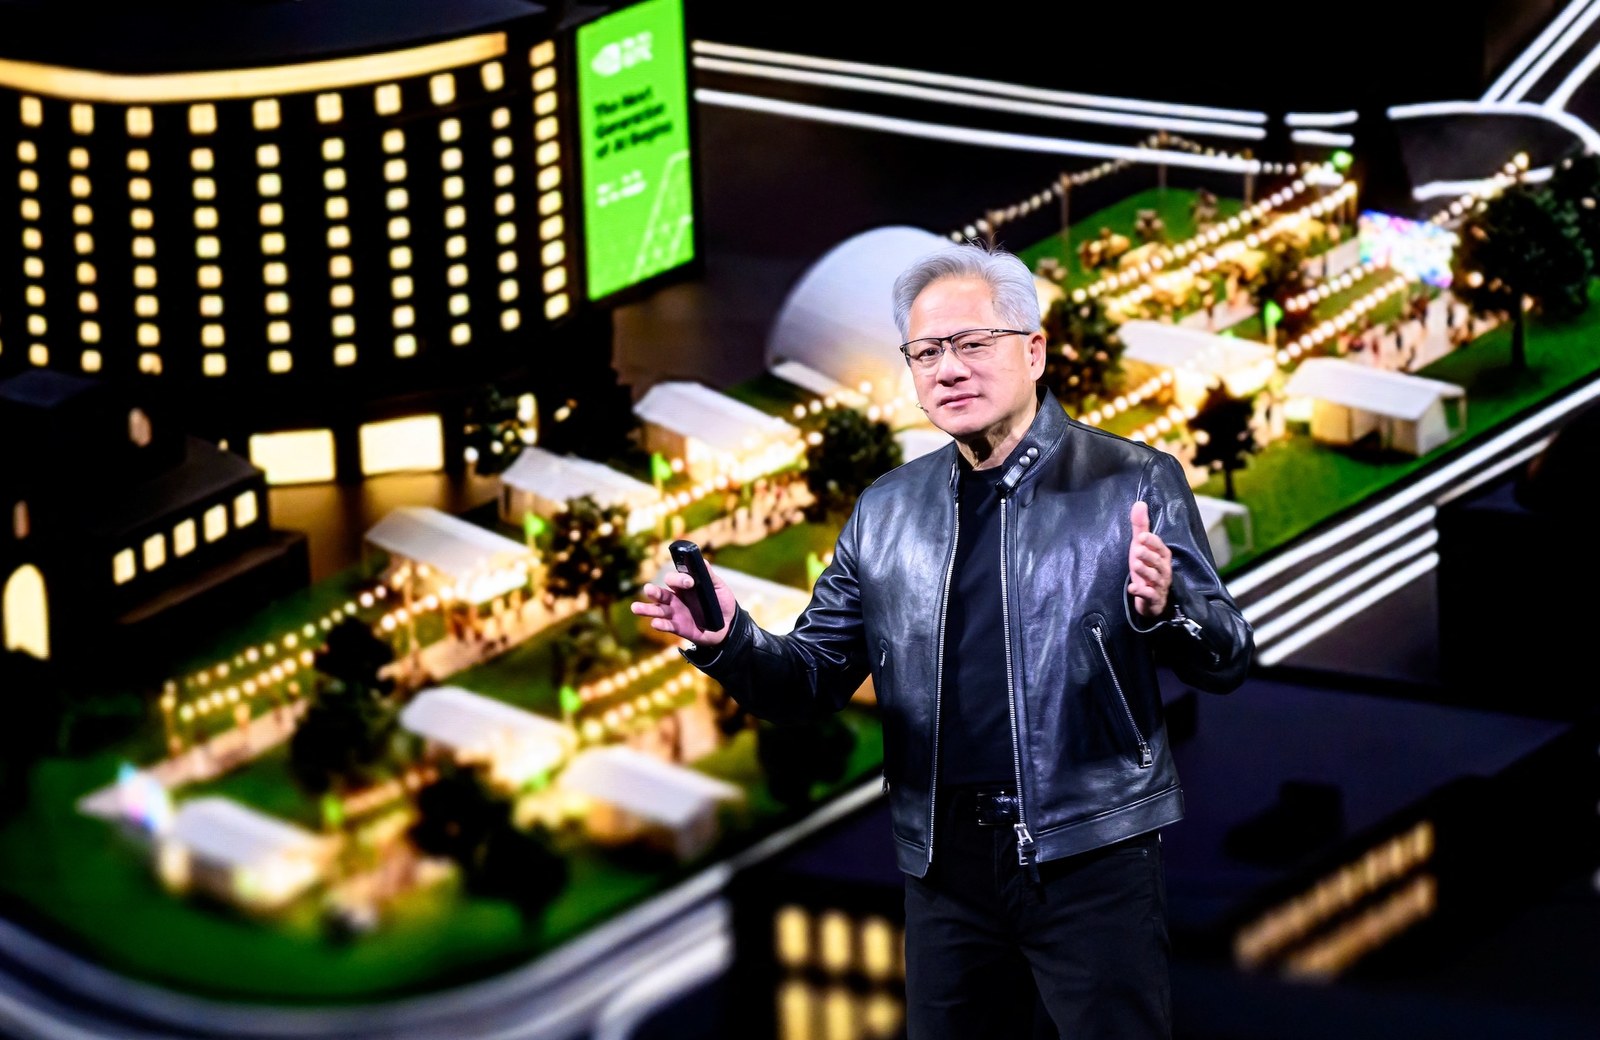
On a stage at Goldman Sachs’ Communacopia+ technology conference on September 10, Jensen Huang was asked about the charge that has trailed Nvidia for more than a year: that the company props up its own demand by investing in the very startups and infrastructure projects that then turn around and buy its chips. He leaned into the question rather than away from it.
“Is that circular?” the Nvidia chief executive said. “If that is, let’s do more of that.” He offered a shorthand for the math he sees: “I put in one, and a hundred comes back.” He was quick to add that the hundred was rhetoric, not a disclosed return figure.
The exchange matters because it puts the company’s leader on the record against the most persistent critique of the AI buildout. Nvidia sits at the center of a capital cycle in which it invests in AI companies, those companies raise money to buy Nvidia’s chips, and the chipmaker’s revenue grows on the strength of demand it partly financed. Critics call it a loop. Huang calls it a bet on customers he believes will grow.
The numbers behind the debate are real. Nvidia has taken stakes in a string of AI companies, from model builders to cloud providers, and its balance sheet has become a way to steer capital toward buyers of its hardware. When one of those companies closes a funding round, a portion of the money often flows back to Nvidia as an order for graphics processing units. That is not a secret; Nvidia discloses the arrangements and has defended them as ordinary strategic investing.
What Huang is pushing back against is the implication that the demand is artificial. His argument, made in different forms over the past year, is that the companies he backs would buy the chips anyway, because they need computing power to serve paying customers. The investment, in that telling, accelerates a sale that was coming, rather than inventing one that was not.
The doubters have not been quieted. The core question hanging over the AI boom is whether the hyperscale cloud providers can earn enough from their own customers to service the debt they have taken on to build data centers. If utilization of that computing capacity slips, the repayment math breaks, and the whole chain from Nvidia down to the startup founders slows at once. Huang’s “one in, a hundred back” line does not answer that question, and he did not pretend it did.
Analysts said the exchange reflects a company that has decided to stop ignoring the circular-financing charge and instead mock it. The risk of that approach is that it can read as dismissive of a legitimate question about the durability of demand. The benefit is that it keeps the conversation on the one metric Nvidia wants investors to focus on: whether the money is coming back.
That metric, for now, holds up. Nvidia’s revenue has more than doubled year over year, and the backlog for its next generation of chips stretches quarters out. The companies buying those chips are not hobbyists; they are the largest technology firms in the world, with access to capital that a downturn would dent but not break.
Still, the circular-financing critique is not going away, because it touches the structure of the entire AI economy rather than any single quarter. Nvidia funds customers; customers buy Nvidia; Nvidia’s results confirm the market’s faith in Nvidia; that faith lets Nvidia fund more customers. Every link in that chain has been solid so far. The question Huang was asked on stage is whether the chain is a flywheel or a house of cards.
The debate is unfolding at a scale that would have seemed impossible three years ago. Nvidia’s market value has crossed into the trillions, and the capital spending of the large cloud providers is measured in hundreds of billions of dollars a year, most of it destined for the kind of chips Nvidia sells. Huang’s defense rests on a simple claim: that spending is backed by revenue from customers who use the computing power for real work, not by a speculative loop.
The company’s own investing arm has become a regular presence in AI funding rounds, backing model builders and the cloud providers that lease them capacity. Each investment carries a disclosure that the companies may also buy Nvidia products, a footnote that critics read as the loop made explicit and that Nvidia reads as ordinary business. The two readings have coexisted for as long as the boom has lasted.
His answer was the flywheel. “If that is circular, let’s do more of that,” is the kind of line a chief executive delivers when he believes the critics will be proven wrong by the numbers. The proof is still arriving, one quarterly report at a time, and the whole market is reading it as closely as he is.