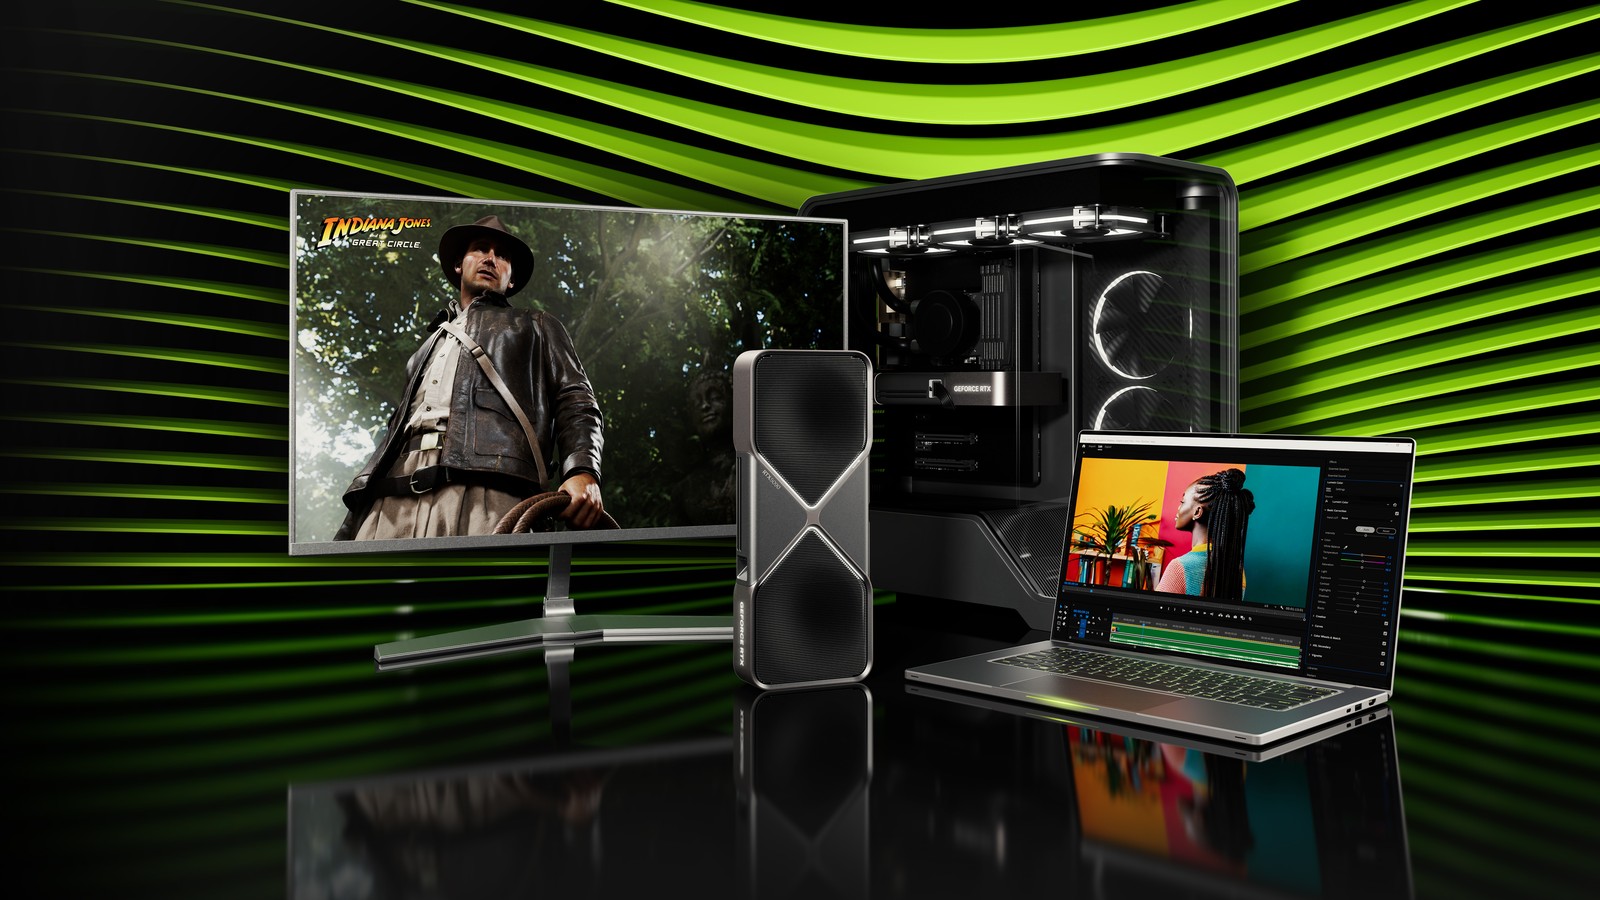
The card lists at 1,999 dollars and, where a buyer can find one, sells for several times that. The gap between the two numbers is what produced the rumor, and the rumor was that Nvidia had stopped making it.
Jeff Fisher, the company’s senior vice president for personal computing, denied that at an event in Taipei this month. The RTX 5090 remains a core product, he told Taiwanese reporters, supply will continue, and what buyers are encountering is insufficient capacity rather than the end of the line.
The rumor had a basis in what shoppers could see. Listings disappeared from some retailers, at least one large American chain showed the card as not carried, and street prices climbed into the thousands of dollars above the suggested price. When a flagship vanishes from shelves, discontinuation is the natural inference.
A second executive pointed somewhere else entirely. Keita Iida, an Nvidia vice president who works with developers, said in a recent interview that the shortage facing ordinary buyers, gamers included, comes from supply chain problems affecting the whole semiconductor industry, memory among them, and that this is not an area the company controls.
The arithmetic behind that claim is not complicated. Each RTX 5090 carries 32 gigabytes of GDDR7, the newest generation of graphics memory, and GDDR7 is produced by the same three companies that make high-bandwidth memory for accelerators: Samsung, SK hynix and Micron. The two products compete for the same wafers and the same packaging lines.
High-bandwidth memory wins that competition on revenue per wafer by a wide margin. A stack of HBM sells for multiples of what the equivalent silicon earns in consumer graphics, and the buyers are the largest companies in the technology industry, contracting years ahead. When capacity is reallocated, consumer graphics is the residual claimant.
That is the mechanism the executives are describing, and it is visible in prices. DRAM contract prices have risen through the year on data center demand, memory makers have converted lines to HBM, and every product that needs discrete memory, from graphics cards to consoles to laptops, has had to bid for what remains.
Nvidia’s own allocation decisions sit on top of that. Data center products account for the overwhelming majority of the company’s revenue, gaming for a small slice, and wafers are finite. A company in that position does not discontinue a flagship, because the flagship supports a platform of drivers, software and partner cards. It ships fewer of them.
The distinction between discontinued and unavailable is not academic for anyone holding the card. A product that is end-of-life stops receiving driver optimizations and eventually loses support. A product that is allocated keeps them. Buyers paying a large premium on the secondary market are, in effect, betting on which of the two they are buying.
There is a history to compare against. The last time graphics cards were this hard to find, in 2021, the constraint was a combination of cryptocurrency demand and packaging capacity, and the shortage lasted about eighteen months. The current constraint is memory, which takes longer to fix because a new DRAM fab is a multiyear construction project rather than a production line that can be rebalanced.
The company’s board partners absorb the same constraint. They buy graphics memory on contracts of their own, build cards around whatever allocation arrives, and their volumes have tracked the memory market rather than demand from system builders. A retail chain that lists the card as unavailable is reporting a purchasing decision, not a statement from the manufacturer.
Retail pricing tells its own story about allocation. Cards that reach a shelf sell at whatever the market bears, and the difference between the suggested price and the transaction price accrues to the retailer or the reseller rather than to Nvidia. There is no shortage of demand at 1,999 dollars, and no mechanism that keeps the card on the shelf at that number.
Iida’s framing is also a boundary claim, and boundaries are worth marking. Nvidia cannot order more DRAM into existence, and it cannot force a memory maker to favor a lower-margin customer. What it can do is choose which of its own products receive the memory it can obtain, and it chooses the ones with the highest margin.
The company’s messaging reflects that split. Fisher’s denial addresses the product’s status, which the company controls. Iida’s explanation addresses the supply, which it does not. Both statements can be accurate at once, and the pair describes a business managing a shortage it did not create and cannot end.
For buyers the practical question is duration. Memory capacity additions scheduled for next year will ease the tightness in the consumer market only after the data center buildout has taken its share, and the buildout is not slowing. Prices at retail will follow availability, not announcements.
What the episode shows is how quickly a supply chain problem becomes a product rumor. A card that cannot be found looks discontinued to the person who cannot find one, and no statement from a stage in Taipei changes the shelf. Nvidia can deny the sunset. It cannot stock the shelf until the memory market lets it.