
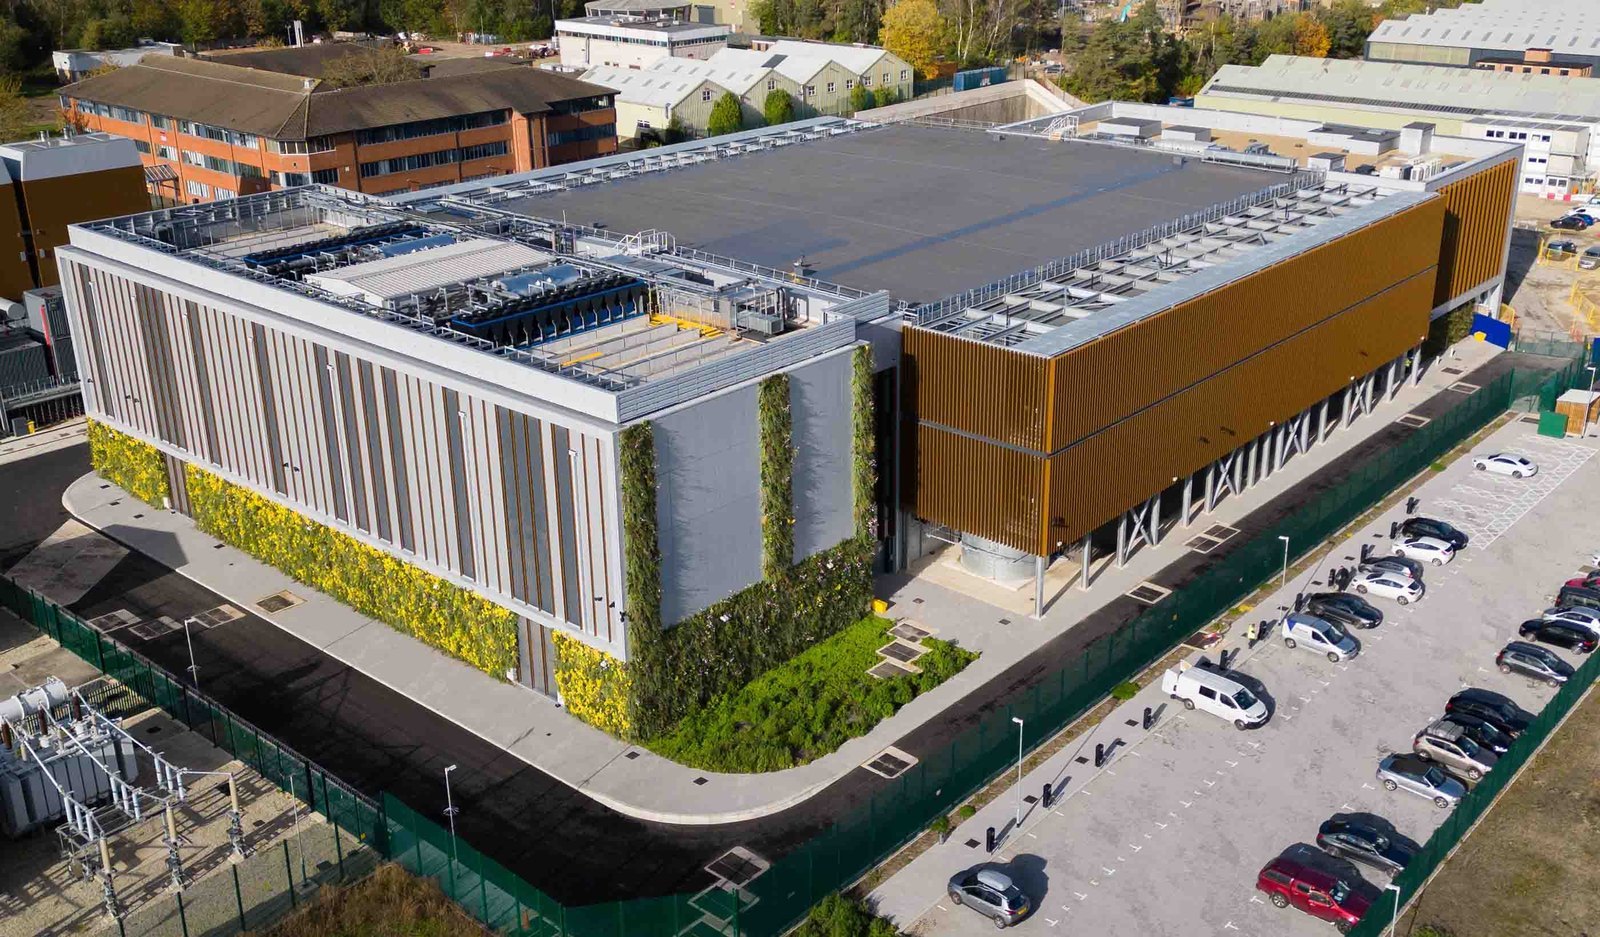
The best tenant in British data centres does not shop for the cheapest rack, cannot be lured to a rival campus and renews on terms its landlord helps set. It is the government.
TPG is in talks with Elliott Investment Management to buy Ark Data Centres, a British operator, at a valuation of about $5 billion, according to people with knowledge of the negotiations. The talks are continuing and may not produce a deal.
Ark was founded in 2005 and is one of the country’s largest data centre operators. It also holds something rarer than space and power: a joint venture with the U.K. Cabinet Office called Crown Hosting Data Centres, set up to serve the public data centre requirements of central government. That structure gives Ark a claim on a tenant that does not churn, does not renegotiate against a cheaper quote and cannot move its workloads without a ministerial decision.
Elliott bought the company in 2012 and explored a sale last year, when reported valuations ran above $4 billion. The mark has moved up by roughly a billion dollars in about twelve months, which says something about what happened to data centre pricing in the interval.
Buyers of this kind of asset underwrite contracted cash flow, not growth. An infrastructure fund’s model is a discount rate applied to leases with a sovereign counterparty, plus a terminal value that assumes the land and the power connection can be re-let at market. That is a different exercise from a hyperscaler lease, where the tenant holds negotiating power, can exit at renewal and often does. Government tenancy inverts the usual risk. The credit is effectively the state’s, and demand is set by policy rather than by one company’s capital budget.
What cannot be replicated quickly is permission. A data centre is a building wrapped around a grid connection, and in Britain the connection queue, the planning process and local consent politics all take years. Existing capacity with power already allocated is therefore worth more than the steel in it. That is the arbitrage TPG would be buying: not the ability to build, but the right to have built already.
Crown Hosting complicates the story. The venture was designed so that departments could buy colocation without each running its own procurement, and it has made Ark the default route for a class of government workloads. It also makes the company a political asset. Contracts with the state get audited, published in part and raised in Parliament. A foreign-owned landlord of government systems invites a question that a landlord of private systems never faces: who controls the infrastructure the state runs on.
That question has been asked before, in other sectors, and the answer has usually been a set of conditions rather than a refusal: security clearances, data residency, a right of first refusal, an obligation to keep investing. A buyer at this price will accept conditions, because conditions are cheap relative to the scarcity they protect.
The seller’s motive is easier to read. A special-situations fund holds an asset whose value now depends on a development pipeline the buyer must fund. Elliott has owned Ark for more than a decade, ran a process last year and is running one again at a higher mark. Selling into an infrastructure buyer’s cost of capital, rather than holding through another build cycle, converts a paper gain into a realized one.
The risk on the other side is a supply response. If planning rules loosen and grid connections accelerate, the premium in existing capacity erodes. Britain has spent years promising exactly that and delivering slowly, which is why the premium has lasted. Energy prices are the second variable, since power is a landlord’s largest cost line and its leases are indexed to something.
There is also the possibility, never entirely absent in British politics, that a government concludes it should own more of its own hosting. Crown Hosting was itself a partial answer to that instinct, a compromise that kept procurement private while the state kept a seat at the table. A change of owner reopens whether the compromise still holds.
For TPG, the wager is narrow and specific: that the British state’s appetite for compute grows faster than its willingness to build, and that whoever holds the buildings in the meantime collects a toll. It is a real-estate bet with a political counterparty, and the counterparty changes its mind on a five-year cycle while the leases run longer.
The price also sets a benchmark. Valuations of data centre operators have moved from “real estate with a technology tenant” to “critical infrastructure,” and every deal at the new level makes the next one easier to justify and harder to walk away from. A $5 billion check for a company that owns buildings in a country with a slow grid is a statement about where infrastructure capital thinks the next decade of demand sits, and it will be quoted in every boardroom that is considering a sale.
What TPG is buying, in the end, is not rackspace. It is the accumulated permissions: the power contracts, the planning consents, the framework status inside government procurement, the relationships that make a campus expandable. Those take a decade to assemble and cannot be bought anywhere else at short notice, which is why the buyer is a fund with a long hold period and a low return threshold rather than a developer with a spreadsheet.
The talks may yet fail, and Elliott has shown it is willing to hold. If they succeed, the check buys a landlord’s position that no competitor can build against inside ten years, sold by a fund that decided ten years was long enough.



