
Before a robot arm can fold a towel, someone has to record a person folding towels. That is the business Humyn Labs is selling, and on Wednesday it raised $47 million to sell more of it.
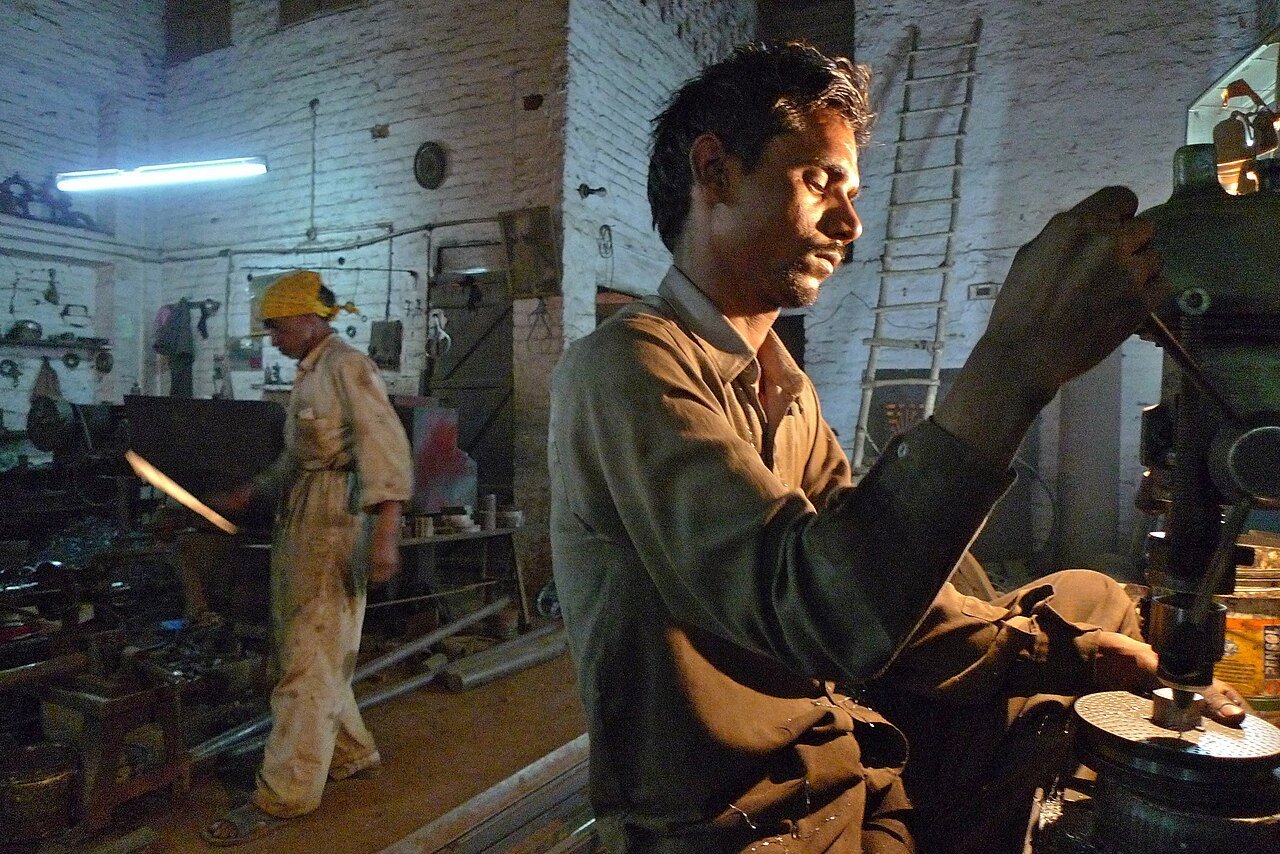
The Indian company said it closed a Series A round split into two parts. Accel led $26 million of equity, and Lighthouse Canton led $21 million of venture debt. The company collects footage and sensor data of ordinary work inside factories, warehouses, farms and homes, then converts it into labeled, traceable training data for robot makers.
The split between equity and debt is the detail worth pausing on. Debt in a Series A is usually a minority slice used to finance equipment. Here it is 45% of the round, which tells you the capital goes into capture rigs, field crews and the cost of paying people to be filmed rather than into software engineers.
Physical training data has become the constraint on humanoid robotics. Language models learned from text that already existed on the internet. Robots have no equivalent corpus, because the motion of a hand closing around a cup has never been written down at scale. Companies building manipulation systems have to commission the recordings themselves, and commissioning recordings is an operations business with crews, schedules, consent forms and travel.
Humyn’s answer is geography. The company runs operations in India, Brazil and South Korea, and keeps offices in San Francisco, London and Seoul. Each market supplies a different kind of work: Korean factories with tight tolerances, Brazilian agriculture with uneven terrain, Indian warehouses with high volume and low automation. The wage differential is the reason the collection can be done at a cost a robot maker will pay.
The company describes its output as traceable, which in this market is a technical and legal claim at once. Traceable means every clip carries its provenance: which device recorded it, where, when, with whose permission. Robot developers need that to prove their training sets were assembled lawfully, and buyers of robots need it to answer questions from regulators.
Privacy is where the collection runs into trouble. A home is not a factory, and footage of a home contains people who did not agree to appear in a dataset even if the resident did. Brazil’s data protection law imposes consent and purpose-limitation requirements that are stricter than India’s, and the European rules that govern work done for British clients are stricter still. Humyn has not published how it handles bystanders, and that silence will be tested as the datasets get larger.
Competition is crowding in from two sides. Data-labeling companies that built businesses on text and images have moved into video and motion capture, using the same contractor networks. And simulation offers a substitute: build the environment in software, generate the demonstrations there, and skip the field work. Nvidia and several startups sell exactly that.
The case against simulation is the gap between a rendered world and a real one. A model trained on synthetic cloth learns the physics of the simulator’s cloth, and a real towel behaves differently when it is damp or caught on a corner. Every robotics team that has tried to move a policy from simulation to a machine has paid for that gap, and the payments are why field data still commands a price.
The case for simulation is cost. A synthetic dataset can be generated in a day and multiplied without limit. Field data costs money per hour and cannot be re-recorded after the fact if the labels turn out wrong. As synthetic pipelines improve, the premium a buyer will pay for real footage narrows, and Humyn’s margins depend on staying ahead of that narrowing.
Accel’s interest is a bet on the shape of the industry rather than on one company. If humanoid robots ship in volume, the firms that supply their training data will look like the suppliers of any other industrial input: thin margins, long contracts, high operational discipline. If the robots stall, the data business stalls with them.
The venture debt adds a fixed obligation to that uncertainty. Lenders to a company of this size typically secure their loans against equipment and receivables and price them with warrants, which means the cost of the round is higher than the equity headline suggests. Humyn will need to convert field capacity into recurring contracts before the debt matures.
What the company has not disclosed is revenue, customer count or how much of its data is resold to more than one buyer. Those three numbers decide whether it is a data vendor with a defensible archive or a services firm that gets paid by the hour. The round buys time to answer the question, and the geography it is built on buys the company a cost structure its American competitors cannot match.
Robots still learn by watching. The question this round poses is whether watching can be industrialized, and whether the industrial version is cheaper than the simulated one.



